The short version: RRSP contributions reduce your tax now but withdrawals are taxed later; TFSA contributions don't reduce tax, but growth and withdrawals are tax-free.
Side by side
| RRSP | TFSA | |
|---|---|---|
| Contributions | Tax-deductible | Not tax-deductible |
| Withdrawals | Taxed as income | Tax-free |
| 2026 limit | 18% of 2025 earned income, up to $33,810, plus unused room | $7,000 (total $109,000 if eligible since 2009) |
| Deadline | March 1, 2027 for the 2026 tax year | December 31 counts against that year |
| Withdrawn room | Not restored | Added back the following January 1 |
| Over-contributing | 1% a month above a $2,000 buffer | 1% a month on the excess |
Which suits you depends on your income now versus in retirement and your goals. This is general information, not financial advice.
FAQs
Is an RRSP or TFSA better?
It depends on your tax rate now versus later; RRSPs help most when your tax rate is higher now than in retirement.
What's the 2026 RRSP limit?
18% of 2025 earned income up to $33,810, plus unused room; your exact limit is on your Notice of Assessment.
What's the 2026 TFSA limit?
$7,000 for 2026; $109,000 in total for someone eligible since 2009.
Plan it in minutes
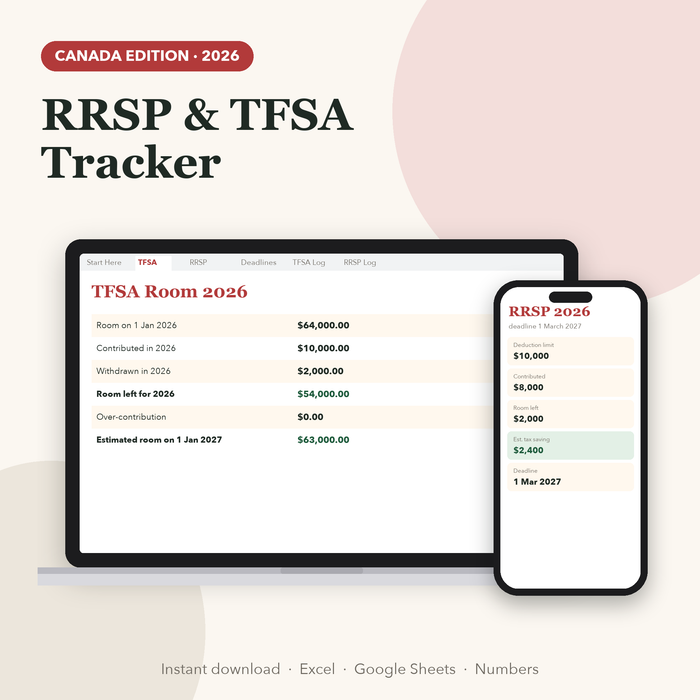
Track both accounts in one place, with room left, over-contribution alerts and the March 1 RRSP deadline countdown.