Allowable expenses are business costs you can deduct from your income before tax. They must be for the business: money taken for personal use doesn't count.
What you can claim (GOV.UK categories)
| Category | Examples |
|---|---|
| Office costs | Stationery, phone bills |
| Travel | Fuel, parking, train or bus fares |
| Clothing | Uniforms |
| Staff | Salaries, subcontractor costs |
| Stock and materials | Things you buy to resell or use in your work |
| Financial costs | Insurance, bank charges |
| Business premises | Heating, lighting, business rates |
| Advertising and marketing | Website costs |
| Subscriptions | Trade or professional journals |
| Training | Courses related to your business |
What you can't claim
- Personal spending, even if paid from the business account.
- Client entertaining.
- The personal share of anything used for both business and home.
Simplified expenses and the trading allowance
Instead of actual costs, you can use HMRC flat rates for vehicle mileage (45p a mile for the first 10,000 in 2025/26) and working from home. Or skip expenses entirely and use the £1,000 trading allowance; you can't claim both.
FAQs
Can I claim my phone bill?
Yes, the business part of it under office costs.
Can I claim lunch or client entertaining?
Generally no: everyday meals and client entertaining aren't allowable expenses.
Should I use the £1,000 trading allowance?
Only if your real allowable expenses are under £1,000; you can claim the allowance or your expenses, not both.
Plan it in minutes
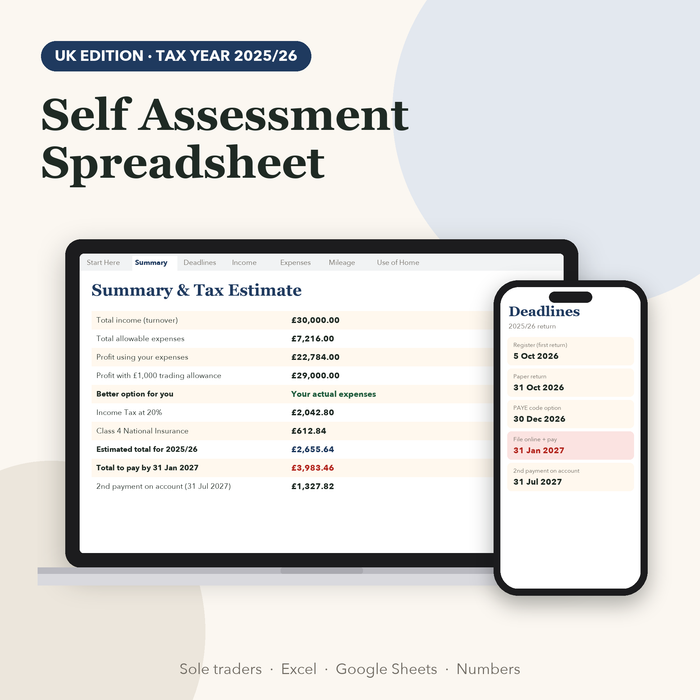
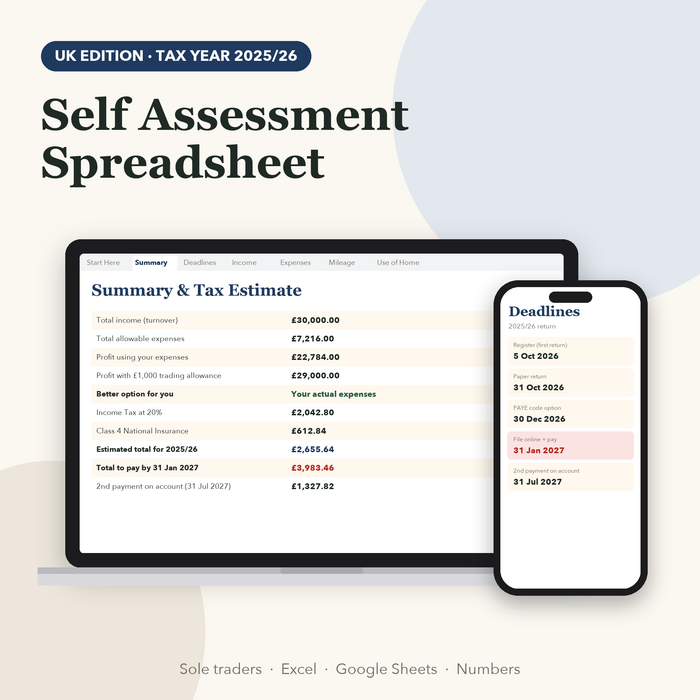
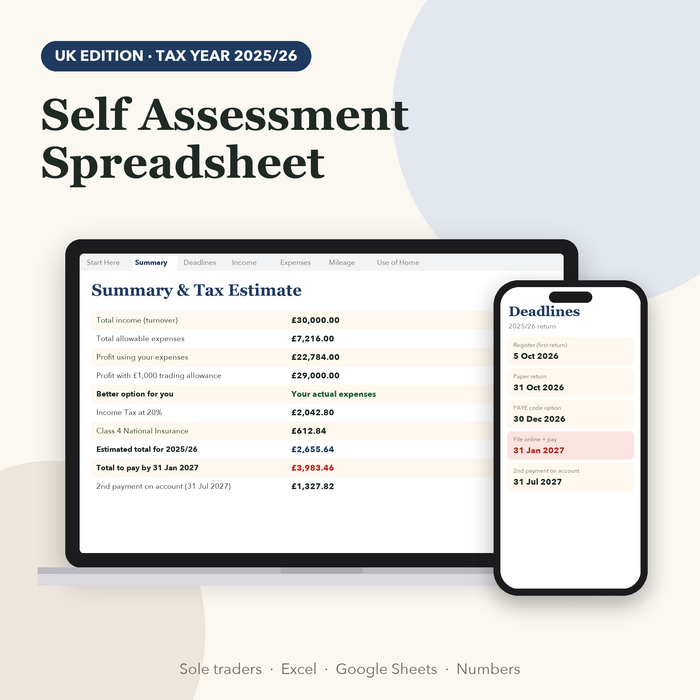
Log expenses with categories that follow the return, keep non-allowable costs separate, and let the spreadsheet check whether the trading allowance beats your expenses.
See the Self Assessment Spreadsheet UK →